Update a saving balance and compare it with a fixed goal
Paper packet. Every task here also exists on screen, where it is checked automatically; answers written on paper are not assessed by Nydus. When you are back at a device, enter your answers there.
1. What you will learn
Update a saving balance and compare it with a fixed goal
2. Starting point
Money paid out reduces a balance; money actually received increases it. Keep today's balance separate from promised future additions.
3. Words for this lesson
Term
What it means
Saving
Keeping funds for later rather than spending them now.
Balance
The amount available at a particular time.
Contribution
Money actually added to the saving amount.
Withdrawal
Money taken out of the saving amount.
Target
The amount needed for a stated goal under the given conditions.
Reconcile
Check that the starting amount and recorded changes explain the ending amount.
4. Saving keeps resources for a later use
Saving money means keeping some available funds instead of spending them now. A learner with five dollars might keep three and spend two on a stated activity. The three dollars remain available for a later use under the conditions of the case. Saving is not a new source of money by itself. The saved amount comes from resources that were already available or have actually been received.
A saving goal names a later purpose and an amount needed for it. For example, a fictional model kit may cost eleven dollars. A learner who has five dollars set aside is six dollars below that goal at the stated price. The arithmetic compares the current balance with the target. It does not tell us whether the kit is the best use of money for that learner.
Waiting can make a larger purchase possible when more money becomes available over time. It also means not using the saved money for another purpose now. That is an opportunity cost. Saving is therefore a choice involving different possible uses at different times, not something automatically better in every situation. A necessary current expense may matter more than an optional future purchase.
Our exercises state the starting balance, additions, withdrawals and target. They also say when each event happens. You will reconstruct the balances and the first time a goal is reached under those assumptions. You will not be asked to choose a real financial product, predict future prices, or decide what another family ought to spend.
Another way: A balance and a contribution are different
A balance is the amount available at a particular time. A contribution is an amount added during a period. If three dollars are already saved and two dollars are added at the end of each week, the balance after one week is five dollars. The starting three dollars are counted once. They are not added again every week unless the case explicitly describes another three-dollar contribution.
After the second two-dollar addition, the balance is seven dollars. We can record the sequence as three at the start, five after one week and seven after two weeks. The balances are not separate piles to add together. Adding three, five and seven would count much of the same money repeatedly. The amount at the end of week two is seven, not fifteen.
This distinction appears in many kinds of records. A jar contains a number of coins now; new coins arrive during a week. A cupboard holds supplies now; deliveries and uses change what remains. The amount at a date and the changes during a period answer different questions. Keeping them separate makes a saving record easier to understand.
Use a clear order for events. 'At the end of week one' differs from 'at the start, before the first addition.' If a target is already reached at the start, the required number of additional weeks can be zero. Do not force every saving question to require at least one new contribution.
Another way: Find the first time the goal is reached
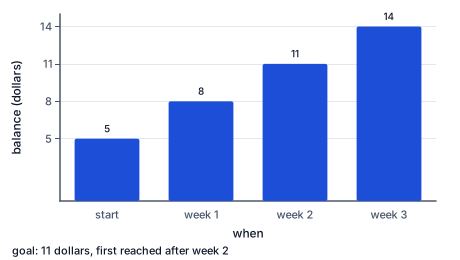
The balance in dollars at the start and after each weekly addition of 3 dollars, starting from 5: 5 dollars at the start, 8 after one week, 11 after two and 14 after three. The goal is 11 dollars. The first bar to reach it is the one after the second week, so the goal takes two weeks; the third week's bar is more than enough.
The bar chart shows the balance week by week; the first bar to reach the goal line answers the question.
Suppose a learner starts with five dollars, adds three dollars after each week, and has an eleven-dollar goal. The balances are five at the start, eight after one addition and eleven after two. The first time the balance reaches at least the target is after the second weekly addition. It takes two additional weeks under this schedule.
The words at least matter. A goal of ten dollars would also be reached after the second addition in this example. Eight is too little after one week; eleven is enough after two. We do not require the balance to equal the target exactly. An amount above the target can meet a purchase price while leaving some money afterwards.
Check the immediately previous balance to show why the answer is the first qualifying time. Saying that the learner has fourteen dollars after three additions proves that three weeks are enough, but it does not show that three is the shortest wait. Since eleven was already enough after two, three is not the first time the target was reached.
For small whole-number examples, a short table or repeated addition is often clearer than a rule written with letters. Start from the actual balance, add the stated contribution one time at a time, and stop when the target is met. Record the number of additions, not the number of numbers you wrote in the table, because the starting row is not an additional week.
Another way: Withdrawals and missed additions change the plan
A saving plan may include money taken out for another stated use. Suppose four dollars are saved, three are added, and two are then withdrawn. The new balance is five dollars: four plus three minus two. A withdrawal reduces the available balance. It does not erase the earlier contribution from history, but both events must appear in the record.
The order can matter when we ask whether a target was reached at a particular moment. A balance may briefly reach a target before a withdrawal and fall below it afterwards. A question asking about money available for a purchase after all events must use the final balance at that time. It should not use an earlier high point as if the withdrawn money remained available.
A promised contribution is not yet part of the current balance. If a case says a contribution arrives next week, do not count it as money available today. If a planned addition is missed, record zero added for that period. Keeping the original schedule unchanged would pretend that money arrived when it did not.
These changes are not reasons to label a person successful or unsuccessful. They are events in the stated record. A family may need to use saved money for an important purpose, or a contribution may change for reasons outside a learner's control. The task is to account for the amounts accurately and update the plan from the information supplied.
Another way: The target also has assumptions
A saving target based on a purchase price assumes something about that price. If a kit costs twelve dollars now, a plan can calculate when a balance reaches twelve under stated contributions. It cannot guarantee that the kit will still cost twelve when the person is ready. In our basic cases, the price is explicitly held fixed so the arithmetic has a definite answer.
If the exercise gives a new price, use the new target from the specified time. A balance of twelve dollars meets a twelve-dollar price but not a fourteen-dollar price. The extra amount needed is two dollars. This is a comparison of supplied amounts, not a forecast that prices will rise. Prices might change in different ways; the case must tell us which change to use.
Similarly, do not invent interest, fees or rewards. A basic saving jar with no interest gains only the amounts actually added. An account example may provide a stated interest rule, but that is a different model requiring additional calculation. The present lesson names zero interest and no fees where those conditions matter, so its simple balance rule stays clear.
The future availability of contributions is another assumption. A schedule saying 'three dollars each week' gives a modeled pattern for the exercise. It is not a promise about every person's future income. A careful conclusion says 'under these contributions and this fixed target' rather than claiming that a real outcome is certain.
Another way: Reconcile the record and explain the choice
A complete saving record can be checked by a single reconciliation: starting money plus all actual additions minus all withdrawals equals ending money. If a learner starts with two dollars, receives additions of three and four, and withdraws one, the ending balance is eight. Two plus three plus four minus one equals eight. Each event enters once with the correct sign.
Compare this ending balance with the target separately. With a ten-dollar goal, eight dollars leaves a two-dollar gap. With a seven-dollar goal, eight is already enough and one dollar would remain after a seven-dollar purchase. A target gap and a purchase remainder are related but different descriptions. Do not report a negative gap as if it were additional money owed.
Explain any waiting time using the previous and qualifying balances. If eight dollars is too little, and the next stated addition of three makes eleven, that next addition crosses a ten-dollar target. This reasoning both gives the time and checks why the earlier time was insufficient. It is stronger than listing a number of weeks without showing the balance sequence.
Finally, distinguish calculation from recommendation. The record may show that keeping two dollars today would advance a later goal. It does not prove that keeping those dollars is always the right choice. Current needs, preferences and other feasible plans matter. Economics helps us make the trade-off visible while leaving those additional judgments attached to the people and purposes involved.
5. A group saves for a reusable display
A fictional community group wants a reusable display costing fifteen dollars, with the price fixed throughout this exercise. The group has four dollars saved at the start. It plans to add three dollars at the end of each week. The money earns no interest, there are no fees, and no other money arrives. These conditions define the basic saving model.
After the first addition, the balance is seven dollars. After the second it is ten. After the third it is thirteen, which is still below the fifteen-dollar target. After the fourth it is sixteen. The first balance meeting the target is therefore reached after four weekly additions. Buying the display then would leave one dollar. The previous balance of thirteen confirms that three weeks were not enough.
Now change one event. Suppose the third week's three-dollar contribution is not made. The balance stays at ten dollars that week, rather than rising to thirteen. A later three-dollar addition brings it to thirteen, still too little, and another brings it to sixteen. The same purchase now requires one additional weekly period under the revised schedule.
This comparison does not blame anyone for the missed contribution. It shows how one changed event affects the record. Nor does it recommend a particular place to keep money or predict a real display price. The result follows from the given starting balance, actual additions, fixed target and timing. If any of those change, the group should update the calculation rather than treating the earlier plan as a guarantee.
6. A tempting mistake
Do not add balances from different dates as if they were separate piles of money. Add actual contributions to the starting balance once, and subtract withdrawals once.
7. Two additions reach the target
Read the starting amount.
5 dollars saved
The starting balance is counted once.
Read the target and contribution.
11-dollar target; 3 dollars each week
The price is fixed and there are no other changes.
Add the first contribution.
5 + 3 = 8 dollars
Eight remains below the target.
Add the second contribution.
8 + 3 = 11 dollars
The balance now meets the target.
Check the first qualifying time.
2 weeks; previous balance 8 dollars
One week was insufficient, so two is the first qualifying time.
8. An overshoot still reaches a target
Identify the initial conditions.
2 dollars saved; target 9 dollars
The goal is to reach at least the purchase price.
Apply two contributions.
2 + 3 + 3 = 8 dollars
Two additions are still insufficient.
Apply the next contribution.
8 + 3 = 11 dollars
The third addition crosses the target.
Calculate the purchase remainder.
11 - 9 = 2 dollars
A balance can exceed the price and still meet the goal.
Check the waiting time.
3 weeks; 8 before, 11 after
The preceding balance confirms that no earlier addition reached the target.
9. A withdrawal changes the final gap
Read the starting balance.
4 dollars
This amount is available before the recorded events.
Record the first addition.
4 + 3 = 7 dollars
An actual addition increases the balance.
Record the withdrawal.
7 - 2 = 5 dollars
The withdrawn amount is no longer available.
Record the second addition.
5 + 4 = 9 dollars
This addition occurs after the withdrawal.
Compare with the fixed target.
12 - 9 = 3 dollars still needed
Use the ending balance after all events.
Reconcile the full record.
4 + 3 - 2 + 4 = 9 dollars
Every event appears once, with additions and withdrawals distinguished.
10. A target is already met
Read the starting balance and goal.
10 dollars saved; target 8 dollars
The target is fixed at the stated purchase time.
Compare the two amounts.
10 is greater than 8
The starting money already covers the price.
Your turn: work this step out. Its working is at the end of the packet.
State the remaining wait and balance.
11. Guided practice
Start with 3 dollars. Add 2 dollars, then 4 dollars. Nothing is withdrawn. The fixed target is 12 dollars. Assume no interest or fees. Give total actual additions, the ending balance after every stated event, and the amount still needed for the fixed target, all in dollars. Use zero if the target is already met.
Your result
Total additions
Ending balance
Still needed
12. Guided practice
Start with four dollars. Add six dollars, then withdraw three dollars. Compare the ending balance with a fifteen-dollar target.
Record the addition.
4 + 6 = after_add dollars
The contribution increases the starting amount.
Record the withdrawal.
after_add - 3 = end dollars
Money withdrawn is no longer available for this goal.
Calculate the remaining gap.
15 - end = gap dollars
The target is compared with the balance after all recorded events.
13. Guided practice
Match each statement to what it records.
Balance
Addition
Withdrawal
Target
The jar holds 7 dollars now
3 dollars were added this week
2 dollars were taken out yesterday
The purchase will require 15 dollars at its fixed price
14. Practice
Start with 5 dollars. Actual additions are 3 dollars and 2 dollars. A 4-dollar withdrawal also occurs. The fixed target is 10 dollars. Assume no interest or fees. Give total actual additions, the ending balance after every stated event, and the amount still needed for the fixed target, all in dollars. Use zero if the target is already met.
Total additions: b0
Ending balance: b1
Still needed: b2
15. Practice
Start with 6 dollars. Add 4 dollars and then 3 dollars. Withdraw 1 dollar. The fixed target is 11 dollars. Assume no interest or fees. Give total actual additions, the ending balance after every stated event, and the amount still needed for the fixed target, all in dollars. Use zero if the target is already met.
Your result
Total additions
Ending balance
Still needed
16. Somewhere new
A community reading group starts with 4 dollars for a fixed 16-dollar display. It actually receives 3 dollars, then no contribution during a missed week, then 5 dollars. It uses 2 dollars of these funds for a stated printing cost. Assume no interest or fees. Give total actual additions, the ending balance after every stated event, and the amount still needed for the fixed target, all in dollars. Use zero if the target is already met.
Your result
Total additions
Ending balance
Still needed
17. Lesson test
Lesson test: one question per skill, one attempt each, no hints. Your answers are checked when you submit.
18. Test question
Start with 2 dollars. Actual additions are 5 dollars and 4 dollars. Withdraw 3 dollars. The fixed target is 14 dollars. Assume no interest or fees. Give total actual additions, the ending balance after every stated event, and the amount still needed for the fixed target, all in dollars. Use zero if the target is already met.
Total additions: b0
Ending balance: b1
Still needed: b2
19. What you can do now
Explain how to update a saving balance and compare it with a fixed goal. Show a fresh example and check its result.
Working for the steps left to you
10. A target is already met, step 3
0 extra weeks; 10 - 8 = 2 dollars after purchase
No new contribution is needed under this case's conditions.